Egy szolgáltató kiválasztása előtt, az online kaszinó vélemények megmutathatnak visszatérő tapasztalatokat a ügyfélszolgálatról, ám keresd meg az eredeti feltételeket is. Az olvasói beszámoló akkor informatív, ha megnevezi a vizsgált területet, és közöl elegendő hátteret. Olvasás közben különítsd el az egyedi eseteket, például a lassú ügyintézést, mert egy panasz önmagában kevés.
Vélemények okos értelmezése
Ellenőrizd a frissítés időpontját, mert a szolgáltatás feltételei módosulhatnak, és egy évekkel ezelőtti panasz ma már nem biztos, hogy irányadó. A használható visszajelzés részletezi az ügy menetét, miközben elkülöníti a feltételezést. A kiegyensúlyozott beszámoló előnyöket és hátrányokat is említhet, így árnyaltabb képet kaphatsz.
Az a játékosbeszámoló ad több támpontot, amely megnevezi a témát, és követhetően fogalmaz. Ne állj meg egyetlen oldalon, és vizsgáld meg a különbségeket, mert csökken az egyoldalúság. Egy magas pontszám nem feltétlenül tükröz minden szempontot, ezért nézd meg az indoklást.
Tájékozódás döntés előtt
Az átlátható oldal közli az üzemeltető adatait, amit hasonlíts össze a hivatalos információkkal. A működési jogosultság részleteit az eredeti dokumentumban ellenőrizd, ne csak reklámszövegre hagyatkozz. Amennyiben a szabályzat ellentmondásosnak tűnik, fontold meg, hogy tovább keresel, és jegyezd fel a kérdést. A véleményekből kiindulhatsz egy ellenőrzési listával, de a jogi adatokat ellenőrizd.
Az ellenőrizhető üzemeltetői adat átláthatóbbá teszi a szolgáltatást, míg a homályosságot ne vedd félvállról. A dokumentumok elolvasása nem merül ki a kezdőoldalban, így megalapozottabban dönthetsz. Rövid ellenőrzőlista segíthet összevetni a szolgáltatókat, ha minden ponthoz forrást keresel.
Promóciók körültekintő összevetése
A látványos ajánlat nem mond el mindent, ezért olvasd el a teljes feltételt. A feltételek között nézd meg a megforgatási előírást, mert a játékok eltérően számíthatnak. Ellenőrizd, hogy az ajánlat mely játékokra érvényes, továbbá van-e kizárás. Egy ajánlattal kapcsolatos panasz esetén nézd meg a leírt körülményeket, és vizsgáld meg a dátumot.
A nehezen olvasható szabályzat nehezen összehasonlíthatóvá teszi az ajánlatot, ezért ne fogadd el automatikusan. Hasonlítsd össze az ajánlatot a bónusz nélküli használattal is, és mérlegeld, szükséged van-e rá. A tudatos felhasználó nem siet a döntéssel, és csak érthető feltételek mellett lép tovább.
Kifizetés valamint adatvédelem
A fizetési lehetőségek kiválasztásakor ellenőrizd a feltételeket, és keresd a kapcsolódó díjakat. A kifizetésről szóló hasznos értékelés kitér az ügyintézésre, ezért könnyebb összevetni a feltételekkel. A személyes online kaszinó értékelés és pénzügyi adatok védelme nem hagyható figyelmen kívül, ezért nézd meg a biztonsági beállításokat. A fiókproblémákról szóló értékelések további ellenőrzést indokolhatnak, ezért ne kezeld bizonyítékként az egyetlen állítást.
Amennyiben kérdés merül fel őrizd meg a bizonylatot, és írd le röviden a történteket. A szolgáltató ügyfélszolgálatától kérdezd meg, hogyan követhető a megkeresés, majd őrizd meg a választ. A homályos ügyintézés újabb ellenőrzést tehet szükségessé, ezért mentsd el a levelezést.
Kínálat valamint játékosi tapasztalatok
A felületet értékelő bejegyzés akkor hasznos, ha konkrét példát ad, ezért keresd a gyakorlati részleteket. A felhasználói visszajelzések olvasásakor vedd figyelembe a saját preferenciáidat, és ne a mennyiséget tekintsd egyetlen mércének. A támogatásról szóló dicséret további részleteket kíván, ezért keresd a kapcsolatfelvétel módját.
Próbáld megtalálni a gyakran ismételt kérdések részt, mielőtt segítségre lenne szükséged, így előre láthatod a folyamatot. Mobilos böngészőben is nézd meg a fontos szabályzatok megnyitását, mielőtt adatot adsz meg. A kellemes kezelőfelület nem szavatolja a problémamentes ügyintézést, ezért ellenőrizd a szolgáltató adatait.
Olvasás után írd fel a nyitott kérdéseket, és ne hagyj figyelmen kívül fontos részletet.
Megfontolt kaszinóhasználat
A vélemények olvasása mellett gondold át, hogy a szerencsejáték belefér-e a saját keretedbe, és állj meg, ha kellemetlenné válik.
A körültekintő tájékozódáshoz hasonlíts össze több forrást, és válaszd a távolmaradást, ha bizonytalan vagy.
Example scenario: a 20-person company gets an email from a project management vendor saying an attacker accessed its billing systems. The company’s card is stored in that vendor’s account. It is also the same card that pays for payroll software, cloud storage, ads and about thirty other tools. If the bank cancels and reissues it, every one of those subscriptions fails on its next charge, and someone has to update payment details on each account by hand.
Most small businesses think about SaaS vendor breach payment risk only after a notice like this arrives. The card number is rarely the most sensitive data a vendor holds, but it is the one that can turn a vendor’s incident into your operational problem within days. This guide explains where the exposure comes from, how different card setups change it, and what to do before and after a vendor reports a breach.
Where your payment exposure comes from
Stored card details
Subscriptions work by storing your card for future charges. Well-run vendors pass card data to a payment processor rather than keeping full numbers themselves, but you cannot always verify how a vendor handles it. Assume any card saved with a vendor could be exposed if that vendor is compromised.
Billing account takeover
An attacker with access to your account at a vendor may be able to change plans, add seats or buy add-ons charged to your card, even without seeing the number.
One card, many vendors
The biggest factor is not the breach itself but how many other things depend on the same card. This is often called the “blast radius”. A card shared across every vendor means one incident touches everything.
Card setups compared
Setup
What a stolen number can do
What breaks if you cancel the card
Admin effort
One company card for all vendors
Spend up to the full credit limit or account balance
Every subscription
Low until an incident, then high
Separate card per vendor group
Spend up to that card’s limit or balance
Only that group’s tools
Moderate
Prepaid card per vendor group
Spend only the remaining loaded balance
Only that group’s tools
Moderate, plus top-ups
Merchant-locked card per vendor
Usually nothing outside that merchant
Only that one vendor
Highest: one card per vendor
Merchant-locked cards, explained
Some card issuers offer virtual cards that lock to the first merchant that charges them. After that first charge, the card declines payments from any other merchant. If a vendor storing a merchant-locked card is breached, the stolen number has little value elsewhere because other merchants’ charges will fail. Issuers that offer this often pair it with per-card spending limits and single-use options.
Merchant locks are a strong control, with some trade-offs:
They protect against reuse at other merchants, not against unwanted charges by the breached vendor itself or through a hijacked account at that vendor.
You need one card per vendor, which can mean dozens of cards to track.
They depend on how the merchant appears in the card network, so a vendor that bills through different entities can cause unexpected declines.
To be clear for readers comparing providers: Vizovcc, discussed below, does not offer merchant-locked cards or per-card spending limits. Its cards limit exposure in a different way, through separate prepaid balances.
Before a breach: a vendor payment hygiene checklist
List every vendor that stores a card. Include the card’s last four digits, the vendor’s billing contact, and how often it charges.
Group vendors by risk and function. For example: finance and payroll, core operations, marketing, and low-cost tools.
Split cards by group. At minimum, keep critical vendors on a different card from the long tail of small tools.
Keep balances or limits close to need. A card that pays $300 a month in tools does not need thousands available.
Turn on two-factor authentication for every vendor billing account.
Write down who responds. Name the person who handles card cancellations and vendor updates.
Template: vendor-to-card list
Vendor
Group
Card (last four)
Charge frequency
Holds company data?
2FA on billing account?
Owner
Replacement priority
Payroll software
Finance
Finance card
Monthly
Yes
Yes
Finance lead
1
Design tool
Marketing
Marketing card
Annual
No
Check
Marketing lead
3
Review the list each quarter and whenever you add a vendor. The “replacement priority” column tells you which accounts to update first if a card has to be replaced.
After a vendor reports a breach: response steps
Identify the card. Use your vendor list to find which card is stored with the affected vendor and which other vendors share it.
Contain it. Freeze or lock the card if your provider allows it, or ask your bank to block it.
Review recent charges on that card for anything you do not recognize.
Secure the vendor account. Change the password, check users and billing settings, and confirm two-factor authentication.
Replace the card and update the vendors that depended on it, starting with the most critical.
Check your own obligations. If the incident also exposed customer data you are responsible for, the FTC’s data breach response guide for business covers securing operations, fixing vulnerabilities and notifying the right parties.
Record what happened and adjust your card grouping if the incident touched more vendors than it should have.
Using separate prepaid cards per vendor group with Vizovcc
Vizovcc offers prepaid virtual cards you buy from one account balance funded with crypto such as USDT, USDC, Bitcoin or ETH. Each card has its own fixed balance, so a stolen number can only spend what is left on that card, not your bank balance or a credit line. You can freeze and unfreeze any card from the dashboard, which helps with the containment step above. Every card supports 3D Secure, which adds a verification step at merchants that use it.
A practical layout: one Vizovcc card for core operations tools, one for marketing tools, and one for the long tail of small subscriptions, each loaded with roughly a few months of that group’s spend. If a vendor in the marketing group reports a breach, you freeze the marketing card, review its charges and replace it, while operations tools keep running. For how the cards are bought and used, see Vizovcc’s virtual Visa and Mastercard overview.
Know the limits. There are no team roles or sub-accounts, so anyone with the login sees all card details: protect that login as carefully as a bank login. Vendors decide which cards they accept, and any merchant can decline a prepaid card, so test before moving a critical vendor over.
FAQ
Is a vendor breach my problem if they never stored my full card number?
Possibly less so for the card, but account takeover and data exposure still matter. Review the vendor’s notice and secure your account either way.
How many card groups should a small business use?
Three or four is a common starting point. More groups reduce blast radius but add admin.
Do prepaid cards replace a vendor risk program?
No. They reduce the financial impact of one type of incident. Vendor reviews, access control and two-factor authentication still matter.
Key takeaways
A vendor breach becomes your problem mainly through shared cards and billing account access.
Merchant-locked cards limit reuse elsewhere but need one card per vendor; not every provider offers them.
Separate prepaid cards per vendor group cap what a stolen number can spend and keep other tools running.
Keep a vendor-to-card list so you can act within minutes of a breach notice.
Pair payment controls with two-factor authentication and basic vendor reviews.
Build your vendor-to-card list this week and see how many tools share each card. If you decide to split them into prepaid groups, take a look at Vizovcc as one option for separate balances per vendor group.
Example scenario: you live in Lagos, Karachi or Cairo and want to pay for a US software subscription. Every “best virtual card” list you find opens with Privacy.com, and the first sign-up step asks for a US Social Security number and a US bank account. The next option on the list is not available in your country. By the third tab you are reading forum threads instead of paying for the tool.
Most virtual card roundups are written for US readers. This one starts from the other side: what can you get if you live outside the US, what does each option require, and where does each one fall short? It covers six options, with their real strengths and limits, and a framework to pick the best virtual card for non-US residents in your situation.
First, why the usual US picks drop out
Privacy.com is the name most lists lead with, and it is a good product for its audience. That audience is narrow: its help center says it is available to US citizens or legal residents aged 18 or over with a checking account at a US bank or credit union, a US phone number and, for most users, a Social Security number. International addresses are not supported. Several other US fintech cards have similar requirements. If you do not live in the US, you need a provider that serves your country or does not depend on a local bank account at all.
How we compared the options
Who can sign up: country availability and what you need to open an account.
How you fund it: bank transfer, card, incoming payments or crypto.
Currencies: whether you can hold or spend in the currency your merchants bill in.
Costs: fees published by the provider, where we could confirm them.
Limits: acceptance, refunds and anything that commonly trips people up.
Fees and country lists change often. Treat every figure below as a starting point and confirm it on the provider’s own site before you sign up.
The options
1. Wise
Wise is a multi-currency account with physical and virtual debit cards. Its pricing pages say you can hold 40+ currencies, and conversions use the mid-market rate plus a separate, disclosed fee. If you already hold the currency a merchant charges in, the card spends it without converting.
Pros: transparent conversion pricing, strong for people who earn in one currency and spend in another, also handles transfers.
Cons: the card is only issued in certain countries. Wise’s list of countries where the card is available covers places such as the EEA, the UK, the US, Canada, Australia, Brazil, Japan, Singapore and a few others in Asia. Countries such as Nigeria, Pakistan and Egypt were not on that list when we checked in November 2026. Identity verification is required.
2. Revolut
Revolut is an app-based account with virtual cards, including disposable cards whose details change after each payment.
Pros: polished app, several virtual cards per account, disposable cards for one-off purchases, multi-currency spending.
Cons: you must live in a country Revolut serves (its sign-up page lists them) and pass identity checks. Features and fees depend on your plan and country.
3. Payoneer
Payoneer is built for freelancers and businesses that receive international payments, and it offers a card linked to that balance.
Pros: available in many countries where Wise and Revolut are not, useful if clients already pay you through it.
Cons: the card is tied to receiving payments, so it suits earners rather than people who just want to pay for a tool. Payoneer’s pricing page lists a 29.95 USD annual card fee, a card currency conversion fee of up to 3.5%, and a separate 29.95 USD annual account fee for accounts that receive less than 6,000 USD in 12 months. Fees vary by region and account type.
4. PST.NET
PST.NET issues virtual cards funded mainly with crypto and is popular with media buyers and teams that run many cards.
Pros: crypto funding, many cards, aimed at advertising and business spending.
Cons: the fee model combines top-up percentages and optional subscription plans, and reviews often mention that top-up fees add up. Check its current pricing page carefully before loading large amounts.
5. Ezzocard
Ezzocard sells prepaid virtual Visa and Mastercard cards paid for with crypto.
Pros: no bank account needed, straightforward purchase of a card with a fixed face value.
Cons: reviewers describe its cards as non-reloadable, so you buy a new card when one runs out. Prepaid acceptance varies by merchant, and user reviews are mixed, so read recent feedback first.
6. Vizovcc
Vizovcc sells prepaid virtual cards from an account balance you fund with crypto such as Bitcoin, USDT, USDC or ETH. Signing up needs an email address, and no bank account is needed to fund it. The catalog lists about 54 cards across Visa, Mastercard, American Express, Maestro, JCB and UnionPay, including US-issued cards and local-currency cards for countries such as Turkey, Argentina, India, Mexico, the Philippines, Canada, Singapore and the UAE.
Pros: card pages show the price and how it splits between the issue charge and the loaded balance, several cards per account, freeze and unfreeze, 3D Secure support, and card pages that show Apple Pay and Google Pay compatibility. Card details appear in the dashboard, often within minutes. You can read how its prepaid Visa and Mastercard cards work, then compare currencies and price splits on each card page.
Cons: funding is crypto only. It is prepaid, so there is no credit line, and acceptance varies because any merchant can decline a prepaid card. Card purchases are final, so pick the card and currency carefully.
Comparison table
Provider
Card type
Funding
Who can sign up
Main limit
Wise
Debit (multi-currency)
Bank transfer, card, incoming payments
Card only in listed countries; ID check
Not issued in many African and South Asian countries
Check whether Wise or Revolut serves your country. If one does and you have a bank account, a multi-currency debit card is often the simplest long-term option, especially if you earn in foreign currency.
If clients already pay you through Payoneer, its card spends that balance without moving money first. Weigh the annual fees against how much you spend.
If you have no supported bank and you hold crypto, look at prepaid crypto-funded providers. Compare how fees are charged (per top-up, per card or per month), whether cards can be reloaded, and which currencies are offered.
Match the card currency to the merchant. Paying a USD subscription from a USD balance avoids a conversion on every renewal.
Test before you commit. Make one small purchase with the merchant you care about most before you load a large balance.
Mistakes to avoid
Choosing on the headline fee alone. A low card fee can hide conversion margins or monthly charges. Add up what a year of your real spending would cost.
Assuming every merchant accepts every card. Some subscription, cloud and API providers decline prepaid cards. Check the vendor’s billing help page first.
Using a card to get around rules. A foreign card does not change tax, currency regulations or a merchant’s country terms. Local rules still apply to you.
Ignoring support. When a payment fails at month end, how quickly you can reach someone matters more than a small fee difference.
FAQ
Can I get a US virtual card without living in the US?
Some providers sell prepaid cards issued by US banks to people abroad, and some multi-currency accounts let you hold and spend USD. What you cannot usually do is open a US bank-linked product like Privacy.com without US residency.
Are crypto-funded virtual cards legal?
Crypto rules depend on your country. The card itself is an ordinary prepaid card once it is funded. Check your local regulations on holding and spending crypto.
Which option is cheapest?
It depends on how you earn and spend. For a bank-connected user spending in several currencies, a multi-currency account is often efficient. For someone paying one USD subscription from crypto, the per-card cost of a prepaid card may be simpler to predict.
Key takeaways
Privacy.com and most US fintech cards require US residency and a US bank account.
Wise and Revolut are strong if they serve your country and you have a bank account.
Payoneer suits people who already receive payments through it, with annual fees to weigh.
Crypto-funded prepaid cards (PST.NET, Ezzocard, Vizovcc) need no bank account but differ in fees, reloading and currencies.
Whatever you choose, match the card currency to your merchants and test with a small payment.
Start with your country and your funding source, then narrow the list. If a crypto-funded prepaid card fits your situation, visit Vizovcc and pick one card for the subscription you need most.
Disclosure: this article was prepared with input from ZenVCC, one of the providers compared below. Details for the other providers come from their own websites and help pages, checked in November 2026. Plans and fees change, so confirm current terms before you sign up.
Picture this example. You cancel a streaming trial, but the charge still arrives because you cancelled on the wrong device. The same month your bank flags a renewal from an overseas software company as suspicious and freezes your main card, which takes your grocery delivery, phone bill and three other subscriptions down with it. One card for everything means one problem hits everything.
Putting subscriptions on separate virtual cards fixes much of that. But “virtual card” covers very different products: debit-linked cards, cards inside a bank-style account, multi-currency cards, credit card numbers and prepaid cards. The best virtual card for subscriptions depends on where you live, which currency your services bill in and how much control you want. This comparison covers five providers with different strengths, then a simple framework for choosing.
What matters in a subscription card
Eligibility: many virtual card services are limited to residents of specific countries or to existing customers.
Recurring-payment support: single-use numbers are great for one-off purchases but usually break renewals. You need a card that stays valid.
Number of cards: one card per subscription only works if the provider lets you hold enough cards.
Controls: merchant locks, spend limits and freeze buttons make it easy to stop unwanted charges. Not every provider offers them.
Fees: monthly plan fees, per-card fees, per-payment fees and foreign transaction fees all add up differently.
Currency: if your services bill in USD or EUR and your bank is in another currency, conversion costs land on every renewal.
Validity: each card expiry means updating billing details on every service that uses it.
The five providers at a glance
Provider
Card type
Who can sign up
Cost
Cards available
Subscription controls
Privacy.com
Virtual cards funded from a linked US bank account
US residents or citizens aged 18+ with a US checking account
Personal plan $0; paid plans $5, $10 or 25amonth.3%foreignfee(0.50 minimum) on the two lower plans
12 to 60 new cards a month, depending on plan
Merchant-locked and single-use cards, spend limits, pause and close
Revolut
Virtual cards on a Revolut account
Revolut customers in supported countries
Virtual cards included on every plan, per Revolut
Up to 20 active virtual cards, one of them single-use; monthly creation limits vary by region
Separate cards per service; single-use cards are not meant for subscriptions
Wise
Virtual cards on a multi-currency account
Eligible customers; not available in all countries
Free for US personal accounts; fees vary by country and transaction type
Up to 3 virtual cards at a time
Freeze a card after setting up a subscription; 40+ currencies
Capital One
Virtual numbers on a Capital One credit card
Eligible Capital One cardholders; not available for debit cards and some credit cards
No fee listed; purchases earn the card’s normal rewards
General-use and merchant-specific cards
Merchant-specific cards, lock or delete individual cards
ZenVCC
Prepaid virtual cards bought from a crypto-funded balance
Users who fund with crypto; identity checks may be requested
Card price ($100 to $340) plus $10 issue fee, $0.10 per payment, no monthly fee
About 50 cards in the catalog, one per service if you like
No spend limits, locks or freeze; can’t complete 3-D Secure code checks; prepaid funds set the ceiling
Provider by provider
Privacy.com: strongest controls for US users
For people who live in the US, Privacy.com has the most complete set of subscription controls in this list. Its free Personal plan includes merchant-locked cards, single-use cards, spend limits and the ability to pause or close any card, with 12 new cards a month. According to Privacy.com’s plan and pricing page, the Plus, Pro and Premium plans cost $5, $10 and $25 a month and raise the card allowance to 24, 36 and 60. The catch is eligibility: you must be a US resident or citizen with a US checking account. The two lower plans also charge a 3% foreign transaction fee, so overseas subscriptions cost more there.
Revolut: many cards inside an everyday account
Revolut’s help center lists up to 20 active virtual cards, including one single-use card, and Revolut says virtual cards are available at no extra cost on any plan. That is enough for a card per subscription for most households. Creation is paced: depending on your region, you can only add a few new virtual cards each month. Single-use cards are designed for one-off purchases, so use the regular virtual cards for anything that renews. It suits people who already bank with Revolut and want everything in one app.
Wise: best when services bill in other currencies
Wise’s strength is currency. Wise’s virtual card page says you can hold balances in 40+ currencies, spend at the mid-market exchange rate with a conversion fee, and hold up to 3 virtual cards at a time. You can set up a subscription and then freeze the card to block unexpected charges. Three cards is too few for one card per service, so Wise works best grouped by category: one card for work tools, one for entertainment, one for trials.
Capital One: virtual numbers on a credit card you already have
Capital One cardholders can create virtual card numbers, either general-use or merchant-specific, and lock or delete them without affecting the physical card. Purchases earn the card’s normal rewards. It is a good fit if you already hold an eligible Capital One credit card. It is not a separate product you can sign up for on its own, it is not available on debit cards, and spending sits on a credit line rather than a prepaid balance.
ZenVCC: prepaid cards without a bank account requirement
This provider takes a different approach from the others. It is a prepaid virtual card platform, not a bank and not a credit product. You fund one balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), then buy prepaid Visa, Mastercard, American Express or Maestro cards from it, one per service if you want. Each card costs its price plus a one-time $10 issue fee, each payment costs $0.10, and there is no monthly fee. Cards stay valid for three years from the day they are ready, which means fewer billing updates across your services.
The limits are worth stating plainly. It does not offer spend limits, merchant locks or a freeze button, so it controls spend through the prepaid amount rather than settings. Cards can’t be topped up from the dashboard, and a payment that asks for a 3-D Secure code can’t be completed, because the dashboard doesn’t show those codes. That rules out merchants and regions where that check is routine. Entry cost is higher than free plans elsewhere, because cards start at $110 including the issue fee. The company also notes that Google Play lists virtual cards as an unsupported payment type, and that some services check whether the card’s country matches the account’s country. ZenVCC’s page on cards for subscriptions lists the cards it suggests for common services and the payment rules to check first.
Which one should you choose?
You live in the US and want the most control: Privacy.com’s free plan covers most needs. Upgrade only if you pay many foreign subscriptions or need more cards.
You already bank with Revolut: use its regular virtual cards, one per subscription, before adding another app.
Your subscriptions bill in several currencies: Wise, grouping services by category across its three cards.
You hold an eligible Capital One credit card: merchant-specific virtual numbers add protection at no listed cost.
You hold crypto, or you want prepaid cards with no monthly fee and long validity: ZenVCC, accepting that controls come from the prepaid balance rather than in-app settings.
How to move your subscriptions onto virtual cards
List every recurring charge from the last 12 months of statements, with amount, currency and renewal date.
Cancel what you no longer use inside each service’s account before moving anything.
Choose your split: one card per service if your provider allows enough cards, otherwise one card per category.
Create or buy the cards and record the last four digits next to each service in a simple spreadsheet.
Update billing details in each service, copying the name and address exactly as the card provider shows them.
Watch the first renewal on every new card. Some services place a small verification charge first.
Remove the old card from each service only after the new one has paid successfully.
A note on fair use
Virtual cards are for organizing and protecting legitimate payments. Locking or emptying a card does not cancel a contract, so cancel inside the service as well. Using a fresh card to claim the same free trial again, or to get around a service’s country or pricing rules, breaks most providers’ terms and can get both accounts closed.
Key takeaways
The right card depends on eligibility first: several strong options only serve US residents or existing customers.
Avoid single-use numbers for anything that renews.
Count the cards you need. A provider that allows three cards suits category grouping, not one card per service.
Compare total cost over a year, including monthly plans, issue fees and foreign transaction fees.
Prepaid cards trade in-app controls for a fixed ceiling and no credit exposure.
Start by listing your subscriptions and the currencies they bill in, then match that list to the framework above. If prepaid cards with no monthly fee and three-year validity fit your situation, compare the options at ZenVCC alongside the other providers here.
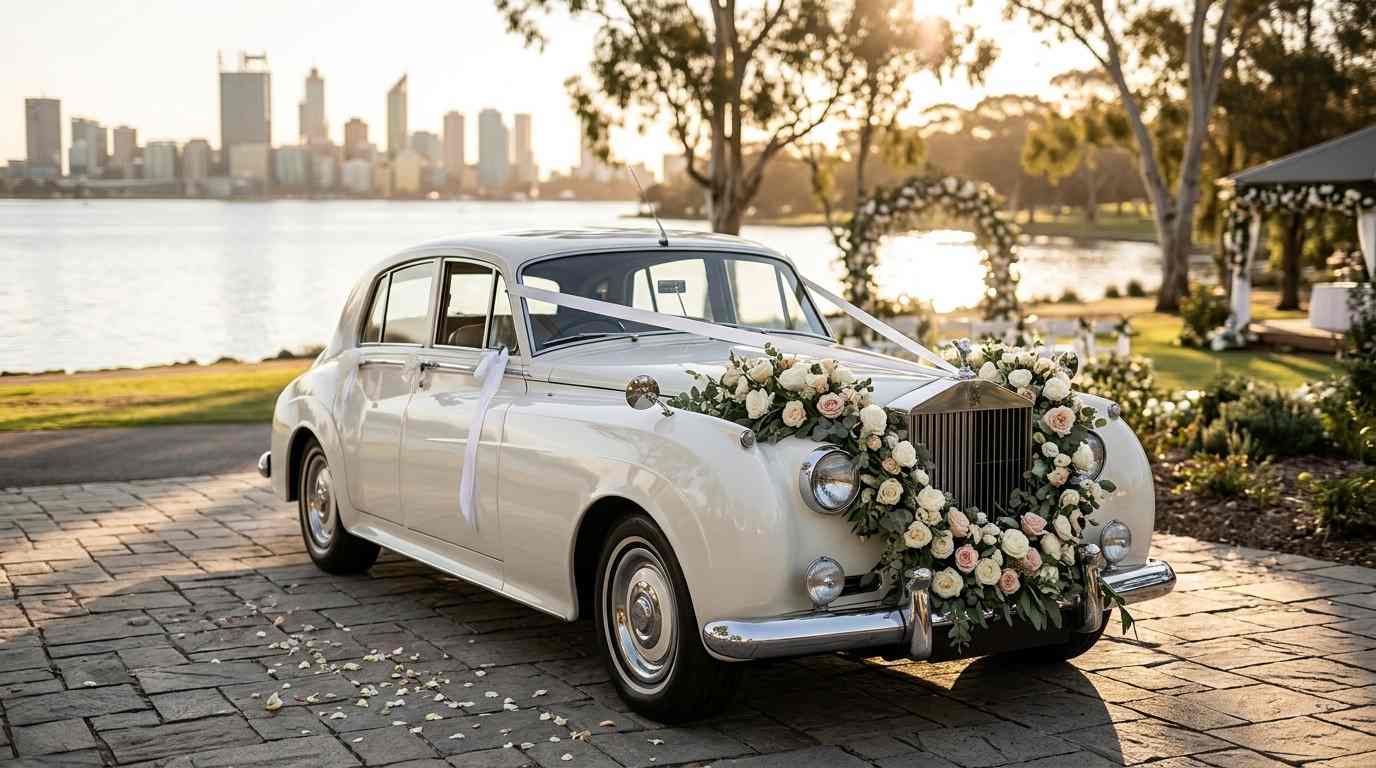
Elegant Charters, a Perth-based chauffeur and private transportation provider, is highlighting its wedding transfer services for couples, families and wedding guests seeking organised transportation across Perth and surrounding areas.
The service provides pre-booked chauffeur-driven transportation for wedding-related journeys, including travel between accommodation, ceremony locations and reception venues. With a fleet that includes sedans, SUVs and larger passenger vehicles, the company offers transport options for couples, wedding parties and groups of guests.
Addressing Wedding Transportation Challenges
Wedding planning involves coordinating multiple arrangements, including venues, schedules, guests and travel between locations. Transportation can become particularly challenging when ceremonies and receptions take place at different venues or when guests are travelling from various parts of Perth.
For couples and event organisers, arranging reliable transport in advance can help reduce logistical complications and make it easier for guests to follow the wedding schedule.
Elegant Charters provides pre-booked private transfers designed to support these requirements, with vehicle options suited to different group sizes and travel arrangements.
A Structured Approach to Wedding Travel
Through its wedding transfer services, Elegant Charters offers chauffeur-driven transportation for couples and wedding guests. The service can accommodate individual passengers, smaller wedding parties and larger groups requiring coordinated travel.
The company provides access to sedans, SUVs, people movers and minibuses, allowing customers to select vehicles according to passenger numbers and luggage requirements.
Its transportation services can include:
Private chauffeur transfers for couples and wedding parties.
Guest transportation between ceremony and reception venues.
Group transfers using larger passenger vehicles.
Hotel and accommodation transfers for wedding guests.
Pre-arranged pick-ups and drop-offs across Perth.
Child-seat options for families travelling with young children.
Customers can arrange their transportation in advance through the company’s online booking platform or request a personalised quote for their requirements.
Vehicle Options and Booking Flexibility
Elegant Charters operates a fleet that includes standard sedans, luxury vehicles, SUVs, people movers and minibuses with capacities of up to 24 passengers, depending on the vehicle.
These options allow the company to accommodate different wedding transportation requirements, from private journeys for couples to group transfers involving family members and guests.
The business also provides 24-hour online booking and reservation enquiries, along with flexible payment options. Vehicle selection and arrangements can be discussed during the quotation process to help match transport requirements with the event schedule.
About Elegant Charters
Based in Southern River, Western Australia, Elegant Charters provides private transportation and chauffeur services throughout Perth and surrounding regions.
Its services cover airport transfers, corporate travel, weddings, special events, cruise transfers, tours, FIFO transportation and long-distance journeys.
The company’s fleet includes sedans, SUVs, people movers, maxi taxis and minibuses. It also offers family-oriented transport options, including baby seats and child-seat arrangements upon request.
Elegant Charters aims to provide convenient, pre-arranged door-to-door transportation through professional drivers, flexible vehicle options and an online booking system.
Executive Comment
Suggested company spokesperson quote – subject to approval:
“Wedding transportation requires careful coordination, particularly when couples, wedding parties and guests need to travel between different locations. Our range of vehicles allows us to accommodate different group sizes and travel requirements, while advance bookings help customers organise their transportation around their wedding schedule,” said a spokesperson for Elegant Charters.
Supporting Wedding Transportation Across Perth
As wedding events continue to involve multiple venues and diverse guest arrangements, organised transportation remains an important consideration for couples and event planners.
Elegant Charters plans to continue supporting customers with private chauffeur and group transportation options for weddings and other special occasions across Perth.
Couples and event organisers can visit the company’s website to review available vehicles, request a quote and arrange wedding transfers in advance.
About Company
Elegant Charters is a private transportation and chauffeur service provider based in Southern River, Western Australia. The company offers airport transfers, wedding transportation, corporate travel, group transfers, tours, cruise transport and long-distance journeys throughout Perth and surrounding areas. Its fleet includes sedans, SUVs, people movers and minibuses, with online booking and 24-hour reservation enquiry facilities.
Media Contact
Company: Elegant Charters – Airport Transfers Perth – Chauffeur Service Perth Location: Southern River, WA, Australia Phone: +61 458 655 640 Email: info@elegantcharters.com.au Website:https://elegantcharters.com.au/
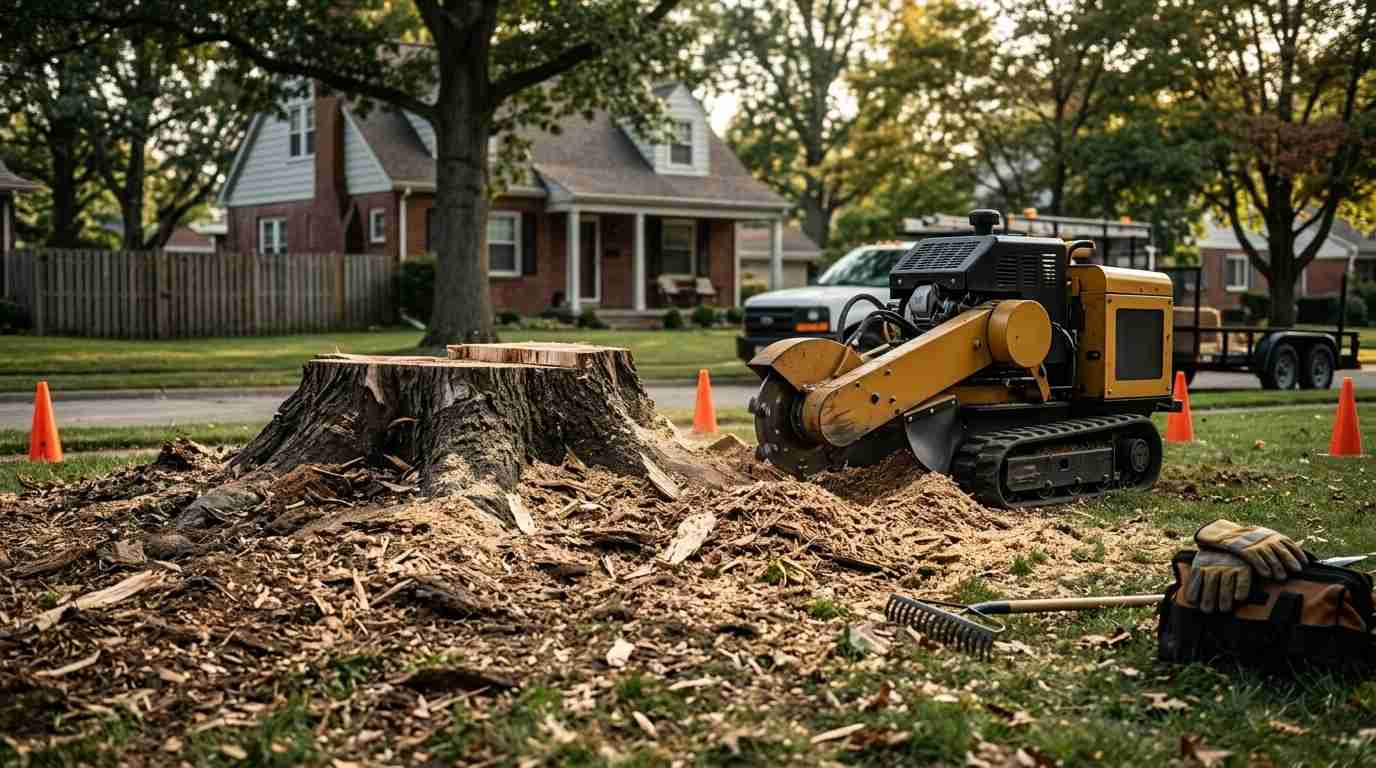
Valentine Services – Stump Grinding is highlighting its tree stump removal services for residential and commercial property owners throughout Cincinnati, Ohio, and Northern Kentucky. The company provides professional stump grinding, surface root removal, and site cleanup to help property owners address leftover tree stumps, improve outdoor accessibility, and prepare their properties for future landscaping projects.
Addressing Common Property Maintenance Challenges
After a tree is removed, the remaining stump can create several challenges for property owners. Exposed roots and partially buried stumps may interfere with lawn maintenance, restrict landscaping plans, and create potential tripping hazards.
Tree stumps can also attract insects and contribute to unwanted regrowth, depending on the tree species and surrounding conditions. Removing these obstacles is often an important step in maintaining usable outdoor spaces.
For homeowners, commercial property operators, property managers, and contractors, professional tree stump removal provides an option for addressing these issues without undertaking extensive excavation.
Company Expands Its Focus on Tree Stump Removal
Valentine Services – Stump Grinding provides stump removal solutions designed to address different property conditions and project requirements. Its approach uses specialized grinding equipment to reduce unwanted stumps below ground level while managing surrounding surface roots.
The company serves customers across the Cincinnati metropolitan area and Northern Kentucky, with services available for residential properties, commercial locations, and contractor projects.
Its service approach emphasizes equipment selection, protection of surrounding landscaping, and cleanup following grinding work.
Tree Stump Removal and Related Services
Valentine Services offers several services to address different stump removal requirements, including:
Residential stump grinding: Removal of unwanted tree stumps from residential yards and landscaped areas.
Commercial stump grinding: Services for commercial properties, managed landscapes, and other business locations.
Surface root grinding: Grinding of exposed roots that may interfere with mowing, landscaping, or property access.
Large stump removal: Specialized grinding for larger tree stumps and challenging removal projects.
Wood chip cleanup: Collection and removal of grinding debris when requested.
Site restoration: Optional topsoil and seed services to help prepare treated areas for lawn recovery.
The company also provides below-grade grinding to help property owners reclaim space previously occupied by tree stumps.
Serving Cincinnati and Northern Kentucky Communities
Valentine Services – Stump Grinding serves Cincinnati and surrounding communities, including Blue Ash, Mason, West Chester, Fairfield, Loveland, Hamilton, Florence, Covington, Erlanger, Burlington, Hebron, and nearby locations.
Its service coverage supports homeowners, contractors, property managers, and commercial customers seeking professional stump grinding and tree stump removal solutions.
The company is licensed and insured and provides free estimates to help customers understand the scope of their stump removal projects before work begins.
Executive Statement
Suggested executive quote — pending company approval:
“Removing a tree is often only one part of improving a property. The remaining stump and surface roots can create additional maintenance challenges for homeowners and property managers. Our goal is to provide a practical stump grinding solution that helps customers reclaim their outdoor spaces while taking care to protect the surrounding property,” said a representative of Valentine Services – Stump Grinding.
Supporting Long-Term Property Maintenance
As property owners continue to maintain and improve their outdoor spaces, stump removal remains an important consideration following tree removal projects.
Valentine Services – Stump Grinding plans to continue serving residential and commercial customers throughout Cincinnati and Northern Kentucky with stump grinding, root management, and cleanup services.
Property owners interested in removing unwanted tree stumps can contact the company to request a free estimate and discuss their project requirements.
About Valentine Services – Stump Grinding
Valentine Services – Stump Grinding provides professional stump grinding and tree stump removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company specializes in removing unwanted tree stumps, grinding surface roots, and addressing outdoor obstacles for homeowners, businesses, property managers, and contractors.
Its services include residential and commercial stump grinding, large stump removal, root grinding, wood chip cleanup, and site restoration. The company serves Cincinnati, Blue Ash, Mason, West Chester, Fairfield, Loveland, Hamilton, Florence, Covington, Erlanger, Burlington, Hebron, and surrounding communities.
Valentine Services is licensed and insured and provides free estimates for residential and commercial stump removal projects.
You have a “virtual card”, a friend has a “prepaid card”, your bank calls yours a “debit card”, and a checkout page rejected one of them for being the wrong “type”. These words sound like four kinds of the same thing, but they answer two different questions. Once you separate them, most of the confusion about why a card works in one place and not another disappears.
Quick answer
– Credit, debit and prepaid describe where the money comes from: a credit line, a bank account or a balance loaded in advance.
– Physical and virtual describe the form the card takes: plastic, or details on a screen.
– So a card can be “prepaid and virtual”, “debit and virtual” or “credit and physical”.
– Merchants usually see the funding type in the card’s BIN, not whether the card is virtual.
Two questions, not four card types
Every card answers two separate questions.
Question 1: whose money pays the merchant at the moment of purchase? This is the funding source.
Credit: the issuer pays the merchant and you repay the issuer later. The limit is a credit line.
Debit: the money comes from your bank account, usually straight away or within a day or two.
Prepaid: the money was loaded onto the card or account before you spend it. You can’t spend more than the balance.
Question 2: what form does the card take? This is the form factor.
Physical: a plastic or metal card with a chip, a magnetic stripe and often contactless.
Virtual: a card number, expiry date and CVV that exist only in an app or dashboard, used for online and in-app purchases.
Tokenized: a card stored in a phone wallet, where a device-specific token stands in for the real number. Both physical and virtual cards can be tokenized, if the issuer supports it.
Mixing the two questions causes most of the confusion. “Virtual” doesn’t tell you whose money is being spent, and “prepaid” doesn’t tell you whether there is any plastic.
The full matrix
Physical
Virtual
Credit
Classic credit card
Virtual number from a credit card issuer, often used for one merchant
Debit
Bank debit card
Virtual debit card from your bank or a fintech app
Prepaid
Gift card, travel money card, payroll card
Prepaid virtual card, often from fintech or crypto-funded providers
All six cells exist and are common. When a merchant says “we don’t accept virtual cards”, it usually means one of the prepaid cells, because that is what it can detect.
What a merchant actually sees
When you type in a card number, the merchant’s payment processor looks up the first digits, the BIN (Bank Identification Number, now usually 8 digits), in a BIN database. The lookup returns:
Network: Visa, Mastercard, Amex and others.
Issuer: the bank or institution behind the card program.
Country: where the card was issued.
Card type: credit, debit or (sometimes, as a separate flag) prepaid.
Product level: consumer or commercial, classic or premium.
The BIN usually says nothing about whether the card is virtual. A virtual debit card from a bank normally looks like any other debit card from that bank. A prepaid card, virtual or physical, normally carries the prepaid flag. That is why “my virtual card was declined” often means “my prepaid card was declined”, and why a debit card can sometimes be read as prepaid if the BIN data is wrong. Research for this post found community threads where a cloud provider treated a card as prepaid even though a BIN lookup said debit.
How authorization differs by funding type
The authorization request looks the same for all three funding types, but the issuer’s decision is based on different things.
Credit: the issuer checks your available credit, called open-to-buy, against the amount, and runs fraud checks. A hold reduces open-to-buy until it is released.
Debit: the issuer checks your account balance, plus any overdraft your bank allows.
Prepaid: the issuer checks the loaded balance. There is usually no overdraft, so the balance must cover the full amount, including any holds that are already pending.
This is why prepaid cards struggle with verification holds and pre-authorizations. Hotels, car rentals, ride apps and cloud providers all reserve money before they charge. AWS, for example, needs a successful authorization of about $1, which is later released, before it verifies an account, according to AWS re:Post. A prepaid card with no spare balance fails that check even though nothing is being bought.
Why some merchants refuse prepaid cards
Merchants treat funding types differently because of risk, not because prepaid money is worse money.
1. Recurring billing risk. A prepaid balance can run out between renewals, so the second or third charge fails.
2. Post-paid billing risk. Services that bill you after use need a card that can absorb a charge later. Google Ads Help, for example, says prepaid cards aren’t accepted for postpay billing, while prepay settings work differently.
3. Deposit and damage risk. Hotels and rental desks want a method they can charge later for damage or incidentals.
4. Fraud models. Some merchants associate prepaid cards with higher fraud or abuse and block the prepaid flag as a rule.
None of this is a judgment on you. It is a rule the merchant applies to the BIN before it looks at anything else, which is why the same card works on one site and fails on the next.
Which card for which job
This is the practical part. Use the matrix to match a card to the payment.
Hotels, car rental, anything with a deposit: a physical credit card. Debit sometimes works. Prepaid usually doesn’t.
Big purchases where dispute rights matter: credit. Protections differ by country and card type, so check yours.
Everyday shopping from your own money: debit, physical or virtual.
Subscriptions you want to cap or isolate: a virtual card, often prepaid, with one card per service so a renewal can never exceed the balance.
Online merchants you don’t fully trust: a virtual card, so a breach exposes a number you can freeze or retire.
Spending money you hold as stablecoins: a crypto-funded prepaid virtual card, for merchants that accept prepaid cards.
Before relying on any card for a specific merchant, run this quick check:
1. Look up the card’s BIN to see its country, network and type.
2. Read the merchant’s accepted payment methods for your country.
3. Check whether the merchant places holds, and make sure the balance covers them.
4. Use the billing address the issuer has on file.
5. Have the 3D Secure step ready.
Where crypto-funded cards fit in the taxonomy
Crypto-funded cards are a growing part of the prepaid cell. According to Visa figures reported by KuCoin News and Techloy, stablecoin-linked cards processed about $5.2 billion in 2025, up 319% year on year, though that was still only about 0.04% of Visa’s total payments volume. [VERIFY: confirm the Visa figures on visa.com before publishing]
VCCBuy’s explainer on virtual cards covers one example in more detail. In taxonomy terms, VCCBuy cards are prepaid and virtual: Visa or Mastercard, funded from USDT, USDC and other supported coins, with the balance credited in USD after the deposit is checked. They are online only, carry no credit check and are treated as prepaid by merchants, with the same limits as any other prepaid card. The provider is not a bank. Its free BIN checker shows the same fields a merchant sees, which is a useful habit with any card.
FAQ
Is a virtual card the same as a prepaid card? No. “Virtual” is the form factor and “prepaid” is the funding source. A virtual card can be credit, debit or prepaid. Many virtual cards sold online are prepaid, which is why the terms get mixed up.
Can a merchant tell that my card is virtual? Usually not from the BIN. Merchants normally see the network, issuer, country and funding type. They can tell a card is prepaid, which is why prepaid virtual cards meet the same restrictions as prepaid plastic ones.
Why does a prepaid card fail when it has enough money for the purchase? Often because of a hold. Hotels, ride apps and cloud providers reserve money first, and on a prepaid card the hold has to fit inside the balance along with the purchase.
Conclusion
Credit, debit and prepaid tell you whose money is spent, while physical and virtual tell you what the card looks like. Merchants make decisions mostly on the first, by reading the BIN. Match the funding type to the payment, keep prepaid balances above any holds, and check a card’s BIN before you rely on it. If a crypto-funded prepaid virtual card fits your needs, VCCBuy is one option to compare with bank-issued virtual cards.
About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write plain-English explainers on how card types, BINs and authorizations work.
Disclosure: the author writes for VCCBuy, which is mentioned in this article.
You’re paying on a site that uses Stripe. You type the card details carefully, press Pay, and get “Your card was declined.” Your bank app shows nothing. You try again and get the same message. What actually happened, and who said no?
Quick answer
1. A Stripe payment can be refused at four layers: the merchant’s Radar rules, the CVC and postal-code checks, 3D Secure, and your issuer.
2. If your bank shows no attempt, the payment was probably stopped by Radar before it reached the bank.
3. You can fix details, funds, 3DS and repeated attempts. You can’t change a merchant’s rule against prepaid cards or cards from your country.
The path of a Stripe payment
When you press Pay, Stripe doesn’t just pass your card to the bank. The payment goes through a sequence, and any step can stop it:
1. Radar risk check. Stripe’s fraud system scores the payment and applies the merchant’s rules.
2. Authentication. If the merchant, the rules or the regulations require it, you get a 3D Secure challenge.
3. Authorization. Stripe sends the request through the card network to your issuer, with the CVC and postal code for the issuer to check.
4. Post-authorization rules. The merchant can still block a payment the issuer approved, for example if the CVC or postal code didn’t match.
The message you see is often the same generic “declined” whichever layer said no. That is deliberate: detailed reasons help people testing stolen cards.
Layer 1: Radar blocks before the bank sees anything
Radar gives every payment a risk score. Stripe’s documentation says that a score of 65 or more counts as elevated risk and 75 or more as high risk, and payments Radar rates at the highest risk level are blocked by default. [VERIFY: current default block behavior on Stripe’s Radar rules page] A blocked payment is marked not_sent_to_network: Stripe never asked your bank.
That explains the most confusing case. If your bank shows no attempt at all, Radar (or a merchant rule) probably stopped it. Calling your bank won’t help, because the bank never saw the payment.
Signals that raise the score include:
An IP address in a different country from the card’s issuing country.
A new email address, a new device and a new card all at once.
Several failed attempts in a short time, especially with different cards.
A billing address or postal code that doesn’t match what the issuer has.
Merchants can also write their own Radar rules. Stripe’s rules can use the card’s funding type and country, so a merchant can block prepaid cards, or cards from certain countries, or allow them only below an amount. Those are the merchant’s business decisions, and no detail you type will change them.
Layer 2: CVC and postal-code checks
The CVC is the three or four digits on the card. The postal-code check compares the code you type with the one your issuer has on file. Stripe passes both to the issuer, and the issuer returns a pass, fail or “unavailable” result.
Many merchants block payments when either check fails, either through Radar’s defaults or their own rules. Stripe’s acceptance docs note that Radar can block payments with a mismatched CVC or postal code.
For buyers, the common traps are:
No address on file. Some prepaid and virtual cards have no billing address until you save one. The issuer then returns “unavailable”, which some merchants treat as a fail.
Format differences. UK and Canadian postcodes with or without the space, US ZIP vs ZIP+4, a postal code with a leading zero dropped.
Wrong address. An old address after a move, or a work address instead of the one the bank has.
Layer 3: 3D Secure
3D Secure (3DS2) asks your issuer to confirm that you’re the cardholder. Often it’s invisible: the issuer approves on device and transaction data. Sometimes it’s a challenge: a code by SMS, a push in your banking app, or a code in a card dashboard.
In the EU and UK, strong customer authentication rules mean many online payments need 3DS. Elsewhere, the merchant or Radar can request it for risky payments.
The failure modes are simple: the challenge times out, the code goes to an old phone number, the bank’s app isn’t set up, or the card doesn’t support 3DS. If the card can’t complete the challenge, the payment fails.
Layer 4: The issuer’s answer
If the payment gets this far, your bank decides. Stripe translates the issuer’s response into its own decline codes:
Stripe decline code
What it usually means
Can the buyer fix it?
insufficient_funds
Balance or credit isn’t enough, including tax or currency conversion
Yes: add funds and retry
incorrect_cvc / incorrect_zip
CVC or postal code doesn’t match the issuer’s records
Yes: correct the details
expired_card
Expiry date is in the past or was typed wrong
Yes: check the date or use the new card
authentication_required
Issuer wants 3DS that wasn’t completed
Yes: retry and complete 3DS
do_not_honor / generic_decline
Issuer declined without a reason; Stripe says this is the most common issuer decline
Sometimes: ask the issuer
card_not_supported
Card can’t be used for this type of purchase
Maybe: ask the issuer whether online or international use is blocked
Blocked by Radar
Payment never sent to the issuer
No: only the merchant can change it
The buyer doesn’t always see the code, but the merchant does. A support message to the merchant with the time and amount often gets you the exact reason.
A buyer’s procedure for a Stripe decline
1. Check your bank app. An attempt there means the issuer declined. No attempt means Radar or a merchant rule stopped it.
2. Check the card itself. Look up its BIN (the first 6–8 digits) to see the network, the prepaid flag and the issuing country, which is what the merchant’s rules see.
3. Fix the details. Re-type the card number, expiry and CVC. Use the billing address and postal code your issuer has on file, in the issuer’s format.
4. Check the amount. Fund the card with the full total, including tax and any currency conversion.
5. Be ready for 3DS. Have your banking app or card dashboard open.
6. Turn off anything that hides your location, such as a VPN or a privacy relay, and pay from your normal connection. A mismatch between your IP and card country raises the risk score.
7. Stop after two failures. More attempts, especially with different cards, look like card testing and raise the score further.
8. Ask the merchant for the decline reason, or ask your issuer if it was an issuer decline.
What you can’t fix
Some refusals are the merchant’s choice: a rule against prepaid cards or a list of countries they don’t sell to. Those apply whatever card you use. If a merchant doesn’t sell to your country, respect that; don’t try to get around it with a different card or location.
Prepaid and virtual cards on Stripe checkouts
Prepaid cards often work on Stripe-powered sites, but they are the cards most often caught by merchant rules, and the ones most likely to have no address on file. Before you use one, check what the merchant will see. VCCBuy runs a free BIN checker that shows a card’s network, type and prepaid flag.
For readers who fund cards from stablecoins, VCCBuy’s own cards are prepaid Visa and Mastercard cards topped up with USDT, USDC and other coins. You can save a billing name and address on each card, and the 3D Secure code is shown in the dashboard for 10 minutes, so no phone number is needed. They are still prepaid, though: VCCBuy is not a bank, and a merchant that blocks prepaid cards will decline them. Bank-issued virtual cards and PayPal are other options where the merchant accepts them.
FAQ
Why does Stripe decline my card when my bank says everything is fine? The payment may have been blocked by Radar or a merchant rule before it was sent to your bank. In that case your bank never saw it. Ask the merchant for the decline reason.
Does a failed postal-code check always cause a decline? No. The issuer reports the result, and the merchant decides what to do with it. Many merchants block mismatches, so it’s worth getting the postal code exactly right.
Will retrying many times eventually work? Usually the opposite. Repeated attempts raise the risk score. Fix the cause, then retry once.
Conclusion
A Stripe decline can come from Radar, the CVC and postal-code checks, 3D Secure or your issuer, and the message rarely tells you which. Check your bank app first, then fix what’s yours to fix: details, address, funds, 3DS and the number of attempts. What’s left is the merchant’s rule, and only the merchant can change it.
About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about checkout risk systems and decline codes, from the buyer’s side of the payment form.
Disclosure: the author writes for VCCBuy, which is mentioned in this article.
Posiadając konto PayPal, łatwo zasilisz swoje konto w kasynie online, co umożliwia szybką grę bez kasyna z wpłata paypal zbędnych formalności.
Zalety korzystania z PayPal przy wpłatach do kasyna online
Użytkownicy mogą wpłacać pieniądze szybko i bezpiecznie, co jest istotne w branży kasyn online. Korzystając z PayPal do wpłat w kasynie, masz pewność szybką transakcję bez dzielenia się informacjami bankowymi z kasynem.
Główne korzyści płynące z użytkowania PayPal to:
Bezpieczne przelewy z skutecznymi zabezpieczeniami.
Błyskawiczne wpłaty konta kasyna bez zbędnych oczekiwań.
Łatwość w przeprowadzaniu transakcji.
Widoczna popularność PayPal w świecie hazardu online.
Możliwość zarządzania środkami z poziomu urządzeń mobilnych.
Rejestracja i konfiguracja konta PayPal – prosty przewodnik
Aby używać PayPal do przelewów w kasynie, należy najpierw założyć konto.Pierwszym krokiem jest założenie konta PayPal, co zajmuje dosłownie kilka minut.
Przypatrzmy się teraz szczegółowej instrukcji wpłaty do kasyna przez PayPal.
Zaloguj się do swojego konta w kasynie online.
Kliknij na zakładkę umożliwiającą zarządzanie depozytami.
Wśród opcji płatności zaznacz PayPal.
Zdecyduj, jaką kwotę pieniędzy chcesz przesłać.
System przeniesie Cię do strony logowania PayPal.
Wpisz dane logowania PayPal i zatwierdź.
Upewnij się, że dane są poprawne i zatwierdź przelew.
Zasilenie konta w kasynie przez PayPal następuje błyskawicznie.
Gdy napotkasz problemy przy płatnościach, wsparcie klienta jest dostępne, aby pomóc.
Najczęstsze pytania dotyczące wpłat do kasyna przez PayPal
W tym rozdziale znajdziesz odpowiedzi na najważniejsze kwestie związane z przelewami do kasyna przez PayPal.
Jak bezpieczne są płatności PayPal w kasynie? PayPal to jedna z najbezpieczniejszych metod płatności online dzięki zaawansowanym systemom szyfrowania i ochrony danych klienta.
Czy wpłaty przez PayPal są natychmiastowe? Zwykle środki wpływają bez opóźnień, co jest ogromnym udogodnieniem dla graczy.
Czy są dodatkowe opłaty za korzystanie z PayPal w kasynie? Warto potwierdzić, czy kasyno nie dolicza dodatkowych kosztów za tę metodę płatności.
Czy mogę wypłacić wygrane środki z kasyna na PayPal? Ważne jest, by przed wpłatą upewnić się, czy kasyno obsługuje wypłaty na PayPal.
Czy PayPal działa na smartfonach i tabletach w kasynach? Wystarczy mieć zainstalowaną aplikację PayPal lub korzystać z wersji mobilnej witryny.
Wskazówki i porady na temat wpłat do kasyna przez PayPal
Sprawdź te wskazówki, aby maksymalnie wykorzystać możliwości PayPal przy wpłatach na konto kasyna.
Upewnij się, że kasyno akceptuje PayPal zanim zaczniesz grę.
Regularnie aktualizuj swoje dane w PayPal, by uniknąć problemów z płatnościami.
Planuj budżet i wpłacaj pieniądze odpowiedzialnie, by gra była rozrywką, a nie problemem.
W razie problemów lub pytań warto skorzystać z pomocy technicznej dostępnej 24/7.
Aplikacja mobilna to doskonałe narzędzie do zarządzania środkami na koncie PayPal.
Podsumowując, wpłaty do kasyna przez PayPal są szybkie, bezpieczne i wygodne, co czyni tę metodę jedną z najchętniej wybieranych przez graczy.
Asher Movers Local & Long Distance has expanded its moving service offerings with a focus on local relocations for homeowners, businesses, students and families in Skokie and surrounding Chicago-area communities.
The new local moving service is designed to support customers who are relocating within the area and need assistance with the logistical demands of moving household or business belongings from one location to another. The service adds to Asher Movers’ existing range of relocation solutions, which includes long-distance moving, commercial relocation, apartment moving, packing, piano moving and other specialty moving services.
Addressing the Challenges of Local Relocation
Even shorter-distance moves can involve considerable planning, packing, transportation and coordination. Customers may need to move between apartments, relocate to a new home, transfer business equipment or coordinate a move around work, school or other commitments.
Asher Movers’ expanded local moving services are intended to provide a structured option for customers who need professional assistance with these aspects of relocation. The company serves customers throughout Chicago and nearby suburbs, including Skokie.
Company Response
Asher Movers provides moving support tailored to different types of relocations. Its service portfolio allows customers to access local moving assistance alongside other services that may be required during a move, including packing and specialty handling.
The company states that its movers are licensed and insured and work with homeowners, businesses, students and military families. Its approach includes careful handling of belongings and moving plans designed around the circumstances of each relocation.
Local Moving Services
Asher Movers’ local moving services are part of a broader portfolio that includes:
The combination of services is intended to accommodate different relocation requirements, from residential moves within the Chicago area to more specialized moving projects.
Company Background
Asher Movers Local & Long Distance is a Chicago-area moving company serving customers in Chicago and nearby suburbs. The company provides local and long-distance moving services as well as commercial, apartment, packing, piano and specialty moving solutions.
The company works with a range of customers, including homeowners, businesses, students and military families. Asher Movers says its licensed and insured movers focus on reliable transportation and careful handling throughout the moving process.
Executive Statement
As no executive name or approved quotation was provided, the following statement is presented as a draft for company approval:
“Local moves can involve many of the same planning and coordination challenges as longer relocations,” said a representative of Asher Movers. “Our goal is to give customers in Skokie and surrounding communities access to dependable moving support that fits the needs of their individual relocation.”
Future Outlook
Asher Movers plans to continue supporting residential and commercial relocation needs throughout Chicago and nearby communities. The expanded focus on local moving services provides another option for customers seeking professional assistance with moves within the area.
For more information about Asher Movers’ local and long-distance moving services, customers can visit the company’s website.
About Asher Movers Local & Long Distance
Asher Movers Local & Long Distance is a Chicago-area moving company providing local moving, long-distance moving, commercial relocation, apartment moving, packing, piano moving and specialty moving services. The company serves homeowners, businesses, students and military families throughout Chicago and nearby suburbs. Asher Movers’ licensed and insured movers provide relocation support with an emphasis on reliable service and careful handling.
Media Contact
Asher Movers Local & Long Distance Email: info@ashermovers.com Phone: 773-638-4167 Website: ashermovers.com